Google Wallet
Google LLC4.4
 Article about Google Wallet
The most revealing moment in a payment app is not the tap at the checkout. It is the one before you leave home, when you pat a pocket, feel your phone, and decide that the rest can stay behind. Google Wallet belongs to that small change in instinct: it turns a device people already carry into a pocket for cards, tickets, passes, and, in some places, digital IDs. Its cultural promise is less about futuristic money than about carrying fewer things without feeling unprepared.
That promise is practical, but it also says something about how we live through phones. We increasingly expect one object to remember the errands, journeys, permissions, and payments that used to require separate bits of paper and plastic. Wallet makes that expectation feel ordinary. Its best trick is not making a transaction look impressive; it is making the physical wallet seem slightly over-equipped.
The app’s contents reflect a present in which identity is assembled from credentials. A bank card lets you pay. A transit pass gets you through a gate. A boarding pass marks a specific journey. A loyalty card keeps a retailer’s relationship with you close at hand. Google Wallet gathers these objects into a tidy, scrollable collection, each one waiting for the moment it becomes useful.
That collection is not universal. What you can add and how you can use it depend on your country, device, bank, transit agency, and the issuer of each pass. Some features, including digital IDs, are limited by location and participating institutions. This unevenness matters: Wallet can look like a single, complete answer while quietly depending on a patchwork of outside systems. The app is a polished front door, not the whole building.
Even so, the arrangement feels distinctly current. We no longer treat the phone as merely a tool for reaching services; it increasingly holds the evidence that we are allowed to use them. A pass is not just information about a train or event. It is a credential presented at a threshold. Wallet makes that shift easy to miss because the interface is calm and familiar, but its contents are a portrait of everyday access.
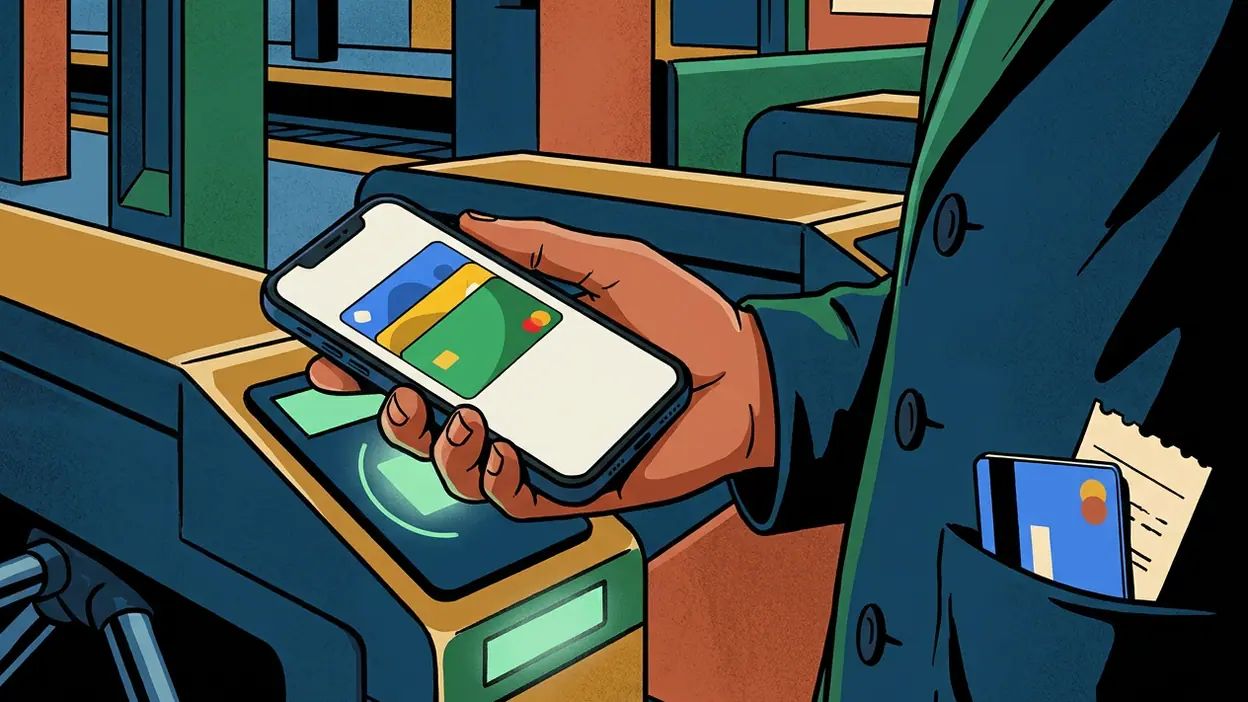
The behavior it normalizes is a move from carrying to retrieving. Instead of checking whether the right card is in the right pocket, you trust that the phone is there and that the item you need can be called up. At a terminal, contactless payment makes the action almost comically brief: wake the device if necessary, hold it near the reader, move on. The less time the ritual takes, the less it feels like a financial decision. It becomes body memory.
That is a real convenience, not just a design claim. In a queue, one fewer search through a bag can keep the line moving. At a station, a transit card or ticket on the phone can reduce the little panic of fumbling at a gate. For travel, keeping a boarding pass with payment cards means fewer places to check when departure gets close. The benefit is strongest in transitions: counter to sidewalk, street to station, security line to boarding gate.
Yet the phone-based ritual has its own terms. A dead battery, a damaged screen, a device left at home, or a reader that refuses contactless payment can bring the old need for backups straight back. Some transit systems support fast access, while others make the user unlock the device or find the right pass. Wallet simplifies the ideal case; it cannot make every institution behave alike. Keeping a physical payment option or another plan is still sensible.
There is a status signal here, though it is quieter than the showiness of a premium phone. Paying by tap can suggest that you are organized, current, and unburdened by clutter. The gesture is quick enough to look effortless, even when it rests on a chain of invisible agreements between the device, bank, network, and merchant. Convenience becomes a kind of polish: not wealth on display, but competence performed without ceremony.
Wallet’s design understands that discretion. Cards and passes are presented as distinct objects rather than flattened into one abstract account. The interface gives a familiar visual cue for each kind of thing, then stays out of the way until the user needs it. The result resembles a digital card case more than a finance dashboard. It is built for recognition and quick access, not for studying spending patterns or managing a household budget.
That boundary is useful. A finance app can easily become a place where every purchase is turned into a chart, alert, or judgment. Wallet generally treats payment as a task to complete, while the bank app remains the place for balances, disputes, and detailed account management. The separation keeps the experience light. It also means the app’s central measure of success is whether the right credential appears at the right time, not whether it helps you understand your finances.
Daily rituals form around those moments. Before leaving, you may check that the phone is charged rather than confirming that a wallet is in your bag. At a cafe, the contactless tap becomes a punctuation mark between ordering and walking away. At a venue, a stored ticket can make arrival feel less like document management and more like simply being expected. These are tiny changes, but repetition gives them weight. The app moves from something you open deliberately to something your hands assume will be there.
People keep it close because it reduces the number of small uncertainties they must manage. A single place for cards and passes is easier to remember than a collection of separate apps and paper slips. That convenience is especially persuasive when a trip involves several kinds of access: getting to the airport, paying for a ride, presenting a boarding pass, then buying something along the way. Each saved search is small; together they make the phone feel like a reliable companion.
There is a less comfortable side to that reliance. The more credentials and routines gather on one device, the more consequential a lost phone or account lockout can become. Digital storage can be protected by device security, and payment systems often use safeguards that keep card details from being shared with merchants in the same way as a plain card number. But protection does not erase dependence. The app asks us to trust not just a screen, but the infrastructure behind it and the ability to recover access when something goes wrong.
That dependence is also revealing because the interface makes it feel private and personal while its usefulness depends on many institutions cooperating. Banks decide which cards are supported. Transit providers determine how passes work. Merchants need compatible terminals. Governments control whether digital identification is available and accepted. Wallet’s composure can conceal this negotiation. Its neat stack of cards is the visible face of a complicated network that users rarely think about until one item fails.
Rivals sharpen the point. Apple Wallet establishes a similar habit for iPhone owners, while individual bank, airline, and transit apps still compete to own specific moments of the journey. The pattern has spread because it answers a common desire: bring the useful credential close to the action. Google Wallet’s particular role is to gather a broad assortment on Android and make those pieces feel like one collection. The competition is less about who invented the digital card than who can make the handoff between everyday services feel most dependable.
Other familiar apps show how different phone rituals can be. Weather apps ask for a quick glance before choosing a coat; entertainment feeds invite a longer stay. Wallet is almost the opposite of a destination. You do not open it to pass time or explore. You open it because something is about to happen: a payment, a ride, an entrance, a journey. Its ideal interaction ends almost as soon as it begins.
That brevity gives the app an unusual kind of stickiness. It may not command attention all day, and it does not need to. Its value accumulates through rare but high-consequence appearances: the card needed at a checkout, the pass needed at a gate, the ticket needed when a show is about to start. A useful app can become essential without becoming entertaining. Wallet earns closeness by being ready at the edges of other activities.
The clearest judgment is that Google Wallet is less a replacement for the physical wallet than a rehearsal for carrying identity through a screen. It makes the rehearsal feel natural, especially when contactless payments and digital passes work as intended. Its limits—regional availability, uneven support, device dependence, and the need for a backup—keep the promise from being complete. Still, the cultural shift is already visible in the ordinary tap: we carry fewer objects because we expect the phone to remember what lets us move. Wallet succeeds by making that expectation feel like common sense.
Google LLC4.4
News
Android and iOS keep tightening control over screens, sounds, and permissions. Zedge still makes personalizing a phone easy, but the operating system now shapes the experience as much as the app does.
News
A practical casebook for deciding whether X earns a place in your daily news routine, from first-time readers to people who depend on it for live updates.
News
A remote app succeeds in the seconds before a show starts. This one gets the basic idea right, but its handoffs and recovery paths need more care.