


Weather & Radar - Storm radar
WetterOnline
News
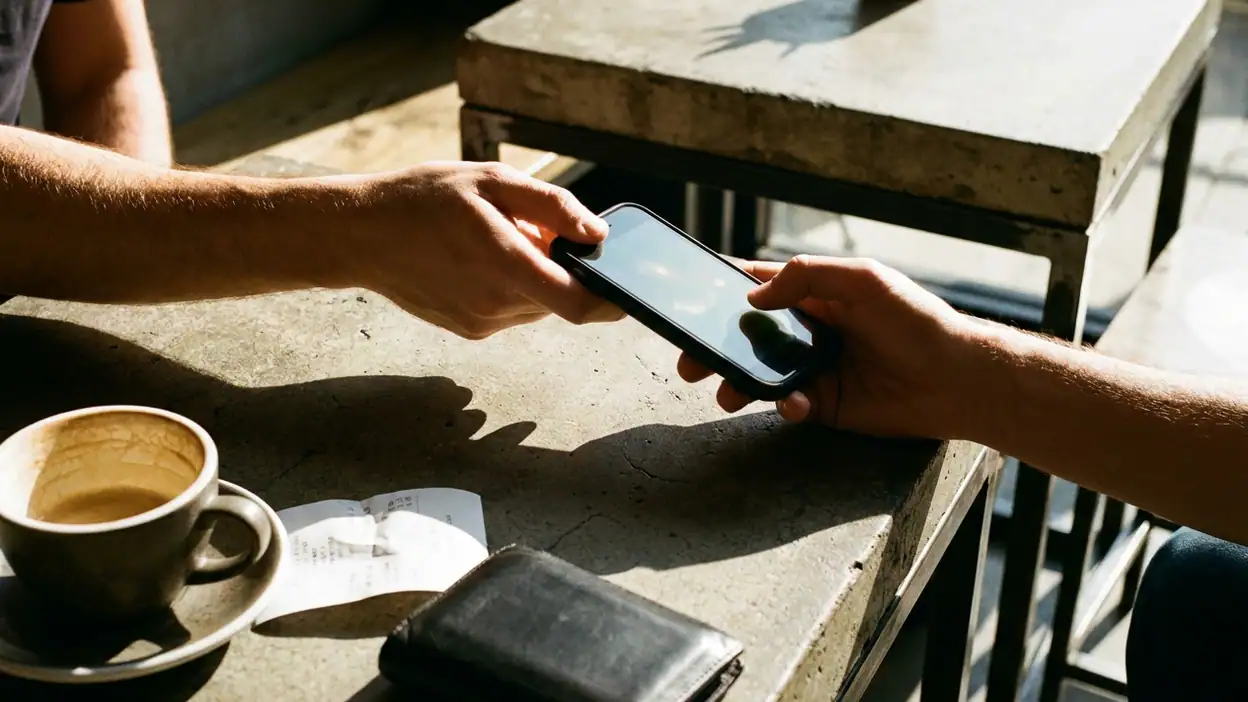
Cash App looks like a wallet until you watch how people actually use it. The core actions are familiar: send money, receive payments, manage a balance, and access related financial tools. Yet the app’s lasting power comes from what happens around those actions. Friends split dinner without opening a spreadsheet, freelancers collect payment through a familiar handle, families send quick help, and online communities turn a payment address into a kind of social calling card. My view is that Cash App is less interesting as a standalone finance utility than as a network of small, repeated agreements. That network is convenient, culturally recognizable, and surprisingly sticky, but it also places trust and safety decisions in the hands of ordinary users.
That distinction matters. A banking app is usually judged by its accounts, transfers, security controls, and reliability. Cash App is judged in public and private conversations: who has it, how quickly someone can pay, whether a username is easy to remember, and whether asking for money feels awkward. The product succeeds because it reduces the social distance between intention and action. “I’ll send you my share” becomes a tap. “Can you help me until Friday?” becomes a payment request. The same compression that makes the app useful also makes mistakes, pressure, and scams travel quickly.
The strongest community feature is not a chat room or a formal forum. It is the shared expectation that a payment can happen with very little explanation. Once a group has settled on Cash App, the app becomes part of the group’s vocabulary. A roommate asks for a handle. A contractor includes a payment name in a message. A parent sends money before a trip. A creator places a payment address near a livestream or post. Each exchange reinforces the habit for everyone involved.
This is a subtle form of network value. The app does not need every user to be deeply engaged every day. It only needs enough people in a person’s orbit to make participation feel normal. That is different from a social network built around posting. Cash App’s community is mostly invisible. It appears at the moment money needs to move, then disappears again. The absence of a public feed is part of the appeal: users can benefit from a network without constantly performing inside it.
That quietness also explains why the app can feel more culturally present than its feature list suggests. A payment handle can circulate through texts, group chats, event pages, creator profiles, and workplace conversations. The app’s identity is carried by users rather than by a single destination where everyone gathers. In that sense, Cash App behaves less like a club and more like a commonly understood custom.
Participation begins with a practical exchange. Someone pays, requests money, receives funds, or checks whether a transfer arrived. Unlike a game such as Lords Mobile: Kingdom Wars, there is no elaborate progression system asking users to return for status, territory, or rewards. Unlike YouVersion Bible App + Audio, there is no central reading routine that organizes a community around shared content. Cash App’s loop is narrower and more ordinary: identify a need, choose a recipient, confirm the amount, and close the obligation.
That narrow loop is precisely why it scales across different relationships. The same basic behavior works for close friends, casual acquaintances, small businesses, and online supporters, although the level of trust should not be the same in each case. The app gives users a common transaction language while leaving the relationship outside the product. It does not need to understand why two people are exchanging money to make the exchange possible.
There is also a useful asymmetry between sending and receiving. Sending is often a one-time act, but receiving can establish an ongoing connection. A freelancer who gets paid through the app may become the default person a client contacts next time. A creator who shares a payment handle may receive occasional support from people who never interact publicly. The network grows through remembered convenience rather than visible membership.
The app’s real social currency is reduced awkwardness. It makes small financial obligations feel routine instead of ceremonial. That is a meaningful design achievement, especially for people who dislike negotiating cash, bank details, or complicated payment instructions. But convenience should not be confused with intimacy. A familiar payment method can make an unfamiliar person feel safer than they actually are.
Most newcomers do not discover Cash App through a long exploration of finance features. They enter because somebody asks them to use it. A friend needs a dinner split. A colleague wants a reimbursement. A seller provides a payment name. A creator mentions support. This invitation-led entry is one of the product’s clearest strengths because it gives the app an immediate purpose.
The first successful payment teaches more than an onboarding screen can. Users learn where to find a contact, how to verify an amount, how to recognize a completed transaction, and how quickly the app fits into a familiar conversation. The experience can feel almost frictionless when the recipient is already known and the amount is modest. That first success turns an abstract finance product into a practical habit.
Newcomers also arrive with different expectations. Some treat the app as a convenient peer-to-peer tool. Others expect a broader financial account, including a payment card, direct deposit, investing features, or access to additional services. The wider the product becomes, the more important it is for users to understand which action they are taking and what protections, fees, limits, or delays may apply. Those details can vary by feature, account status, location, and current policy, so users should verify them inside the app’s official documentation rather than rely on a friend’s summary.
The social invitation can be both helpful and risky. A trusted friend may guide a newcomer through the basics, but a stranger can use the same conversational tone to create urgency. “Send this now,” “verify your account,” or “pay a small fee to receive funds” are not community rituals; they are warning signs. Cash App’s low-friction entry makes it important to slow down precisely when another person is trying to speed the interaction up.
The ecosystem is held together by repetition. Weekly rent transfers, shared groceries, birthday contributions, travel expenses, tips, reimbursements, and small acts of family support all create recurring moments in which the app becomes the expected answer. None of these rituals is dramatic. Their combined effect is powerful because they remove the need to renegotiate the payment method every time.
Group expenses are especially revealing. In a group chat, one person often becomes the organizer, collecting several small payments after an event or purchase. That person is not a moderator in the formal sense, but they perform a community role: setting the amount, clarifying the reason, tracking who has paid, and reminding people without turning the exchange into a confrontation. Cash App supports the transfer, while the social labor remains human.
Creator support follows a different rhythm. A musician, streamer, artist, writer, or local organizer may mention a payment handle during a moment of attention. Supporters choose whether to contribute, often outside a formal subscription structure. The ritual is lightweight and personal, but it can be inconsistent. A creator may receive a burst of payments after a successful post and little afterward. There is no guarantee that visibility converts into dependable income.
Seasonal and emergency use adds another layer. People may send money for a holiday, a move, a medical need, or a sudden shortfall. In those moments, the app becomes part of a support network. That can be genuinely valuable, but it also raises the emotional stakes. A payment request connected to distress can be difficult to evaluate objectively, especially when the sender is a stranger using a compelling story.
Creators extend Cash App beyond its core function by teaching audiences how to use it in public. They demonstrate the language of support: a handle in a profile, a request during a broadcast, a contribution link near a project, or a payment prompt after a performance. The creator supplies context and trust cues that the app itself cannot provide.
This contribution is strongest when the creator explains what support does. A clear request for a specific project, service, or goal gives the audience a reason to participate. It also establishes boundaries. Supporters can decide whether they are paying for work, making a gift, or responding to an emergency. Vague appeals may generate attention, but they make the relationship harder to understand.
Creators also become informal safety educators. Experienced users warn followers not to share login codes, not to send money to impersonators, and not to trust screenshots as proof of payment. These warnings often circulate through posts and comments faster than formal help content. Still, community advice is uneven. A confident creator can repeat an outdated assumption, and an audience may treat popularity as evidence of financial expertise.
There is a limit to what creator culture can add. Cash App is not a publishing platform, and its payment function does not independently verify a creator’s identity, work, or claims. The surrounding social channel carries most of that responsibility. Users should treat an appealing profile, a familiar name, or a persuasive message as context, not proof.
Every payment network has friction, and Cash App does not eliminate it so much as relocate it. The interface may make sending money easy, but users still have to decide who deserves trust, whether the amount is correct, and what happens if the relationship changes. A roommate who pays late, a client who disputes a charge, or a friend who repeatedly asks for advances can turn a simple transfer into a social problem.
There is also friction around reminders. The person collecting money must decide how often to follow up and how direct to be. A request can feel neutral in one group and accusatory in another. Because the app records a financial obligation more clearly than a casual promise, it can sharpen tensions that might otherwise remain vague.
Privacy creates another fault line. Sharing a payment handle is not the same as sharing a bank account number, but it still connects a person to a financial identity. Users may not want a public username associated with their real name, workplace, location, or online persona. Creators in particular must balance discoverability against unwanted contact. A payment address that is easy for supporters to find may also be easy for impersonators, harassers, or persistent strangers to copy.
The app’s social simplicity can therefore produce a strange contradiction. It is easier to ask for money, but not necessarily easier to discuss money. Cash App reduces the mechanics of payment while leaving questions of fairness, consent, privacy, and repayment fully intact.
Users can see some safety prompts, account controls, reporting paths, and transaction warnings, but the full moderation system is not visible from ordinary use. That is normal for a financial service, yet it makes the community ecosystem difficult to evaluate from the outside. We can observe the user-facing rules and the results of enforcement, but not every detection model, review process, appeal standard, or decision threshold.
That uncertainty matters because financial abuse is often conversational before it becomes transactional. Scammers impersonate friends, employers, support agents, romantic partners, or buyers. They create urgency, promise a reward, or claim that a payment must be made to unlock a refund. The app can provide warnings and controls, but it cannot fully moderate conversations happening in text messages, social networks, marketplaces, or livestreams.
Users should assume that a completed transfer may be difficult to reverse, depending on the circumstances and the specific transaction. Before sending money, verify the recipient through a separate channel, inspect the account details carefully, and resist requests for passwords, security codes, or remote access. Official support should be reached through official channels, not through a number or link supplied by an unexpected message.
It is also important not to overstate what can be verified from public information. Cash App’s policies and features can change, and availability may differ by region or account. A review can assess the visible participation model and common user experience, but it cannot responsibly promise that every dispute will be resolved in a particular way or that every suspicious account will be removed immediately. The ecosystem’s safety depends on platform systems, user judgment, and the behavior of outside services together.
The network is most valuable in situations where many people need to exchange modest amounts quickly. Splitting a meal is the obvious example, but the same logic applies to shared rides, club dues, informal tutoring, local events, small freelance jobs, and family support. The value comes from interoperability at the social level: people already know how to ask for a handle, recognize the app, and complete the basic action.
That value is strongest when the payment is embedded in an existing relationship. Friends know how to resolve a mistake. A client has a way to confirm a freelancer’s identity. A family member can call if something looks wrong. In these cases, the app’s network reduces administrative effort without having to become the relationship itself.
The network is weaker at the edges. Paying an unknown seller, responding to a cold message, or sending money after a stranger creates urgency removes the trust scaffolding that makes peer payments comfortable. The same familiarity that helps a friend pay for groceries can make a scam look ordinary. Network size is not the same as network safety.
Comparison with other mobile products makes this clearer. Cricbuzz - Live Cricket Scores gains value from shared attention: users return because matches unfold in real time and conversation follows the score. Weather & Radar - Storm radar gains value from shared practical relevance, especially when conditions affect a whole area. Cash App gains value from shared readiness. Its community is not watching the same event; it is prepared to complete the same kind of exchange.
Cash App’s ecosystem has a durable foundation because money-related habits are difficult to replace once a group has settled on them. People do not want to compare five payment methods before splitting a bill. They want the method their friends, clients, and relatives already recognize. Every successful transaction lowers the chance that the group will switch for no compelling reason.
Durability is not guaranteed, though. Trust can erode after a high-profile scam, a frustrating account restriction, a confusing policy change, or a dispute that users feel was handled poorly. Financial products also compete through banks, card networks, digital wallets, and newer payment services. A rival does not need to win every use case; it only needs to become the default in enough important relationships.
The product’s expansion creates both resilience and risk. Additional financial tools can make the app more useful between payments, giving users more reasons to return. They can also make the experience harder to understand. The broader the account becomes, the more users need clear explanations about balances, transfers, fees, eligibility, timing, and protection. A community built on simple peer payments can become less confident if the surrounding financial system feels opaque.
Long-term health will depend on whether Cash App preserves the trust that made its informal network attractive. That means reliable core transfers, clear communication, strong account protection, responsive support, and restraint around social pressure. The app does not need to become a full social network. It needs to remain a dependable layer beneath the communities people already have.
After looking at the habits around Cash App rather than just its buttons, I see a product whose community is real but unusually quiet. Users contribute handles, reminders, context, trust, and warnings. Organizers keep groups moving. Creators translate attention into support. Friends and families turn a financial tool into a routine. None of this requires a public feed, and that is one of the app’s smartest qualities.
But the ecosystem is only as strong as the relationships surrounding each payment. Cash App can make a trusted exchange faster; it cannot manufacture trust where none exists. It can reduce the embarrassment of asking for a small amount; it cannot settle whether the request is fair. It can provide safety controls; it cannot inspect every conversation that leads to a transfer.
My final judgment is favorable, with a firm qualification. Cash App has earned cultural relevance because it turns ordinary financial cooperation into a nearly invisible habit. Its network value appears in the tiny moments that keep groups functioning, not in flashy community features. Use it with people and organizations you can verify, treat urgency as a warning rather than a reason to hurry, and remember that convenience is not protection. The community around the app is useful precisely because it is familiar; keeping that familiarity healthy is a shared responsibility between the platform and everyone who uses it.
WetterOnline
News
Pizza Ready! turns restaurant growth into a brisk, tactile routine. It beats some mobile tycoons on immediacy, but its shallow decisions make the long game harder to recommend.
News
Messenger earns its place by turning quick questions, shared plans, and calls into one low-friction habit. Its best features save time; its crowded edges still need restraint.
News
The smartest part of this quiz game is not the promise of a big virtual prize. It is the small, revealing decision to ask for help—or trust your own answer.